Tucson Lease Report Nov. 7-11, 2016
Tucson Lease report 3-13-16The following commercial leases were reported to the Real Estate Daily News for the Tucson Lease Report from November 7 thru 11, 2016.

INDUSTRIAL – 750 E. OHIO ST., TUCSON
XO Windows, LLC renewed their lease with Ohio Street Building No. 2 Ltd., LLLP, and expanded their space for a total of 12,000-square-feet at 750 E. Ohio St., Suites 1, 3 & 4 in Tucson.  Cushman & Wakefield | PICOR Industrial Specialists handled this transaction.  Rob Glaser, SIOR, CCIM, represented the landlord and Russell W. Hall, SIOR, GSCS and Stephen D. Cohen, represented the tenant. [mepr-show rules=”58038″]Tenant Phone: 520.455.9039[/mepr-show]

RETAIL – 625 E. WETMORE ROAD, TUCSON
Osher Lifelong Learning Institute at the University of Arizona, dba OLLI-UA, leased  approximately 5,070-square-feet at 625 East Wetmore Road, Suite F-109. The space is located within Tucson Place Shopping Center, which is anchored by Walmart, Best Buy, OfficeMax, Petco, Ace Hardware, and Beall’s. The tenant will use the space for education classes for OLLI-UA’s members. The Landlord, Tucson Place Partners, LLC, was represented by Andy Seleznov, Melissa Lal, and George Larsen of Larsen Baker, LLC.  Debbie Heslop, CCIM, of Volk Company represented Osher Lifelong Learning Institute. [mepr-show rules=”58038″]Asking lease rate: $14.00 – $38.00 SF/YR NNN; Tenant Phone: 520.626.9039[/mepr-show]

OFFICE – 6260 – 6296 E. GRANT RD., TUCSON
Mutterperl Medical Diagnostics Clinic has leased a 4,910-square-feet of space at Wilmot Professional Plaza, located on Wilmot Rd., just south of Grant Rd. The Premises will be used as a general medical practice office, with related administrative uses. They are scheduled to open for business in March 2017.  Andy Seleznov and Melissa Lal represented the Landlord, Larsen Baker. [mepr-show rules=”58038″]Tenant Phone: 520.795.9300[/mepr-show]

INDUSTRIAL – 3450 S. BROADMORT DR., TUCSON
Advanced Print Management, LLC leased a 4,000-square-foot industrial building located at 3450 S. Broadmont Dr., Suite 114 in Tucson, from Tin Cup Properties, LLC.  Advanced Print has specialized capabilities in mailing, in-house printing and bindery.  Jeff Zellet and Ron Zimmerman, Commercial Specialists with Cushman & Wakefield | PICOR, handled this transaction.  Jeff Zellet represented the tenant and Ron Zimmerman represented the landlord. [mepr-show rules=”58038″]Asking lease rate: $0.65 SF/MO Modified Gross; Tenant Phone: 623.466.6350[/mepr-show]

INDUSTRIAL – 1010 E. PALMDALE ST., TUCSON
B/E Aerospace, Inc leased 3,520-square-feet at 1010 E. Palmdale Suite 110 from Foothills Business Ventures, LLC.  Gary Emerson of GRE Partners, LLC represented the Landlord and John Slattery of CBRE represented the tenant. [mepr-show rules=”58038″]Asking lease rate: $0.75 – $0.90 SF/MO Modified Gross; Tenant Phone: 520.733.1733[/mepr-show]

OFFICE – 2020 N. FORBES BLVD., TUCSON
CSDVRS, Inc. leased 2,074-square-feet at 2020 N. Forbes Blvd., Suite 104 in Tucson, from Santo Tomas Partners, LLP.  Brandon Rodgers, CCIM, Principal with Cushman & Wakefield | PICOR, represented the landlord and Bob Pischke with Property Management, Inc., represented the tenant in this transaction. [mepr-show rules=”58038″]Asking lease rate: $12.50 SF/YR Modified Gross[/mepr-show]

RETAIL – 4660 E. CAMP LOWELL DR., TUCSON
The Twisted Tandoor leased 2,700-square-feet of restaurant space from Swan Retail, LLC.  Located within the Shops at Creekside, 4660 E. Camp Lowell Dr. in Tucson, JAM Culinary Concepts, the parent company of Vero Amore and Noble Hops, will operate the restaurant which is a rebirth of the popular Indian food truck.  Aaron LaPrise, Retail Specialist with Cushman & Wakefield | PICOR, represented the landlord and Jayme Fabe with NAI Horizon, represented the tenant in this transaction. [mepr-show rules=”58038″]Tenant Phone: 520.551.0368[/mepr-show]

RETAIL – 170 W. FORT LOWELL RD., TUCSON
Emily’s Hair Salon, LLC leased 1,800-square-feet at 170 W. Fort Lowell Rd. in Tucson, from R Legacy Irrevocable Trust.  Brandon Rodgers, CCIM, Principal with Cushman & Wakefield | PICOR, handled this transaction. [mepr-show rules=”58038″]Tenant Phone: 520.887.5246[/mepr-show]

INDUSTRIAL – 1013 S. EUCLID AVE., TUCSON
PM 4, LLC leased 1,780-square-feet at 1013 S. Euclid Ave. in Tucson from Rich Rodgers South, Inc.  Brandon Rodgers, CCIM, Principal with Cushman & Wakefield | PICOR, handled this transaction.

INDUSTRIAL – 2341 S FIREBUS AVE, TUCSON
Sonoran Desert Natural Products, LLC leased 1,750-square-feet at 2341 S. Friebus Ave., Unit 18 in Tucson, from Oak Properties.  Rob Glaser, SIOR, CCIM, and Brandon Rodgers, CCIM, Principal with Cushman & Wakefield | PICOR, handled this transaction. [mepr-show rules=”58038″]Asking lease rate: $0.55 SF/MO Industrial Gross[/mepr-show]

RETAIL – 7930 E. SPEERWAY BLVD., TUCSON
Foot Massage has leased a 1,500-square-foot space at Speedway Pantano Square, located on the SE corner of Speedway Blvd. and Pantano Rd. The Premises will be used as a reflexology and foot massage studio and for related products and services. They are scheduled to open for business in January 2017.  Andy Seleznov and Melissa Lal represented the Landlord, Larsen Baker

RETAIL – 1110 S. WILMOT RD., TUCSON
Steve Graves, dba Steve’s Mobile Wash, leased approximately 1,482-square-feet of retail space at 1110 S. Wilmot Road, Tucson, Arizona, from Roath Properties, LLC.  Frank Arrotta of Tucson Realty & Trust Co. represented the Landlord and the Tenant in the transaction. [mepr-show rules=”58038″]Tenant Phone: 520.293.2625[/mepr-show]

RETAIL – SE CORNER of ORANGE GROVE RD and RIVER RD., MARANA
Smoothie King has leased a 1,200-square-foot space at Marana Marketplace, located on the SE corner of Orange Grove Rd. and River Rd. in Marana. The Premises will be used for the retail sale of smoothies, juices, vegetable drinks, blended products and related products and services. They are scheduled to open for business June 2017.  Andy Seleznov and Melissa Lal represented the Landlord, Larsen Baker, while Michael Laatsch, of CBRE, represented the Tenant.

INDUSTRIAL – 3957 E. SPEEDWAY BLVD., TUCSON
In Deus, LLC leased 1,100-square-feet in Central Point Business Plaza, 3957 E. Speedway, Suite 205 in Tucson, from Central Point Tucson, LLC.  Jeff Zellet, Commercial Specialist with Cushman & Wakefield | PICOR, handled this transaction.

RETAIL – 4811 E. GRANT RD., TUCSON
Roadhouse Cinemas has leased a 1,031-square-feet of office space at Crossroads Festival, located on the NE corner of Grant Rd and Swan Rd. The Premises will be used as for general office purposes. They are scheduled to open for business in November 2016.  Andy Seleznov and Melissa Lal represented the Landlord, Larsen Baker. [mepr-show rules=”58038″]Tenant Phone: 520.468.7980; Asking lease rate: $16.00 – $18.00 SF/YR Modified Gross[/mepr-show]

RETAIL – 6125 E. SPEEDWAY BLVD, TUCSON
Relax Foot Massage leased 950-square-feet in Monterey Village Shopping Center, located at the southwest corner of Speedway Blvd. and Wilmot Rd. in Tucson, from Monterey Village, LLC.  Greg Furrier, Retail Specialist with Cushman & Wakefield | PICOR, represented the landlord in this transaction.

OFFICE – 9100 N. SILVERBELL RD., MARANA
Farmer’s Insurance Agency, Louis Aquino Agent, has signed a lease for a new office location at 9110 N. Silverbell Road., Suite 120, Marana, AZ in the Shoppes at Continental Ranch located at the southeast corner of Tangerine and Silverbell Roads. Craig Finfrock of Commercial Retail Advisors, LLC represented the Landlord, Shoppes at Continental Ranch, LLC, and the tenant was not represented in this lease transaction. The new office will be 900-square-feet and is planned to open December 1, 2016.

INDUSTRIAL – 3959 E. SPEEDWAY BLVD., TUCSON
Complete Appearance leased 777-square-feet of warehouse space in Central Point Business Plaza, 3959 E. Speedway, Suite 304 in Tucson, from Central Point Tucson, LLC.  Jeff Zellet, Commercial Specialist with Cushman & Wakefield | PICOR, handled this transaction. [mepr-show rules=”58038″]Tenant Phone: 520.326.7372[/mepr-show]

RETAIL – SE CORNER of ORANGE GROVE RD and RIVER RD., MARANA
Tucson Youth Football & Spirit Federation, Inc. has leased a 709-square-foot space at Marana Marketplace, located just south of the SW corner of Speedway Blvd. and Craycroft Rd. The Premises will be used for general office purposes and for related products and services. They are scheduled to open for business December 2016.   Andy Seleznov and Melissa Lal represented the Landlord, Larsen Baker, while Greg Boccardo, of Boccardo Realty, represented the Tenant. [mepr-show rules=”58038″]Tenant Phone: 520.322.9779[/mepr-show]

Submit sale and leases to [email protected].


Phoenix Lease Report Nov. 7-11, 2016

20161108_oldnavygrandopening_0014-editThe following commercial leases were reported to the Real Estate Daily News for the Phoenix Lease Report from November 7 thru 11, 2016.

RETAIL – 16435 N. SCOTTSDALE RD., SCOTTSDALE
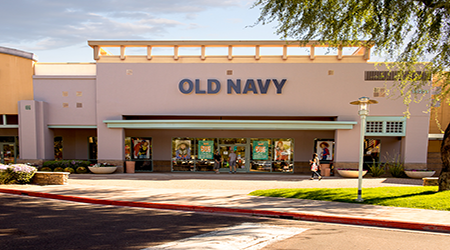
Velocity Retail Group’s Darren Pitts and Dave Cheatham represented Old Navy (a division of Gap, Inc.), in a lease at the Scottsdale Promenade shopping center located at the southeast corner of Frank Lloyd Wright and Scottsdale Road.  The 11,008-square-foot store is celebrating their grand opening beginning November 9, 2016.  The shopping center is owned by an entity controlled by Excel Trust, L.P. and represented by Mike Ord of the D.L. Slaughter Co.

The Scottsdale Promenade shopping center has over 566,000-square-feet of retailers including Nordstrom Rack, Sacks Off 5th, Ulta Beauty and Steinmart.  Old Navy is strategically located adjacent to Nordstrom Rack.

“Old Navy has served their customers in this shopping center since 1999 and will continue to provide great value and fashion trends in this new location within the same shopping center,” said Pitts, executive vice president at Velocity Retail. Cheatham and Pitts have worked with Gap Inc. since 1994, and were part of the initial roll-out of the Old Navy brand in Arizona.  Today Old Navy is one of the largest apparel brands in the world, operating more than 1,000 stores across the US, Canada, Puerto Rico & Japan.

RETAIL – 8041 N. BLACK CANYON HWY., PHOENIX
A Retail Lease for 8,893-square-feet within The Camp at Black Canyon at 8041 N. Black Canyon Hwy. in Phoenix, AZ to United HealthCare Urgent Care was recently consummated. The owner of the center is BKM Black Canyon 103, LLC.  Jared Lively of Rein & Grossoehme represented the Landlord and Tyson Switzenberg with JLL represented the Tenant on this transaction.

RETAIL 28243 N. TATUM BLVD., PHOENIX
A restaurant lease for 5,869-square-feet within Dynamite Creek shopping center at 28234 N. Tatum Blvd. in Phoenix, AZ to Tailgaters Sports Bar and Il Primo Pizza. was recently consummated. The owner of the center is Dynamite Creek, LLC. Jared Lively of Rein & Grossoehme represented the Landlord and Brad Balbo of SRS Real Estate represented the Tenant on this transaction.

Submit sales and leases to [email protected]


Yun: Impact to Real Estate with Trump Presidency

trump1Lawrence Yun, Chief Economist of National Association of Realtors, in  classic Yun-style opined recently on how the real estate market could be impacted by Donald Trump’s victory and Republicans controlling both chambers of Congress.  Though Mr. Trump is a real estate man, his policy platform has been largely vague on real estate proposals.

Yun’s opinions on how certain real estate issues may play out under President Trump and their potential impact to consumers follow:

  1. There will no doubt be a short-term stimulus to the economy. A combination of tax cuts and government spending in the form of upgrading nation’s infrastructure and for national defense will provide a short boost to the economy in the first half of 2017. Inflation will likely kick a bit higher from a faster GDP growth and that will lead to modestly higher interest rates. Accompanying gains in consumer confidence will further move the economy higher. Should the faster GDP growth be sustained and arise out of higher productivity, then inflation will be manageable. Moreover, more jobs will automatically mean more tax revenue, which will lessen budget deficit. Should, however, the stimulus impact give only a short-term boost and not be durable then a much larger budget deficit will force interest rates notably higher. The future generation will be saddled with more debt.
  2. The trade deficit will surely rise in 2017. That’s because a growing economy will allow Americans to drink more Italian wine, drive German sports cars, watch Korean dramas, and play Japanese game consoles. More vacation trips to Cancun and London are also likely. These activities always happen when consumers regain confidence about their financial well-being. Should tariffs be raised to lessen the trade deficit, consumers will face higher prices. If exports and imports significantly decline, then history has repeatedly shown that recession and job cuts soon follow. Most economists believe job training and re-training via community colleges are much better ways to help those who lose jobs from technological automation and from international trade.
  3. There will be more gyrations in the stock market. Wall Street will cheer because of less government regulation but will frown on restrictive international trade policies. The current leader of the Federal Reserve, Janet Yellen, may be asked to step down and this perceived intrusion into what should be an independent institution may be viewed by the financial market as unsettling. Perhaps Mr. Trump relishes in his unpredictability. But the rise of uncertainty in the financial market will hold back corporate investment spending decisions. History says that economic dynamism thrives on the rule of law and not on whims of policy uncertainty. Institutions of law matter much more than any one person or a group of people.
  4. Changes to Dodd-Frank financial regulation will occur in some form. A clear positive would be the lifting of compliance costs imposed on small-sized banks. Around 10,000 local and community banks have traditionally been the source of funding for construction and land development loans. With less regulatory burden, these small banks can make more loans and will boost home building activity – something that is needed in the current housing shortage situation. But changes to financial regulations on large banks like Goldman Sachs and Wells Fargo could again lead us back to the days of cowboy capitalism and consequent exposure to a massive taxpayer bailout.
  5. There could be a move away from stringent mortgage underwriting to more normal lending. Credit is still tight for mortgages as evidenced by very high credit scores among those who are getting approved. An important reason for overly-conservative lending is due to the exposure of random lawsuits by the government on lending institutions in recent years. To the degree that the Trump Administration makes it very clear as to what is and what is not an infraction then more mortgages will be provided to consumers. Should the Trump Administration create an environment of “we will sue you” then the lending institutions will retrench and shut off mortgage access to many consumers.
  6. There could be less regulatory land-use and zoning burden for home construction, and thereby lower the cost of building. In recent years, newly constructed home prices have been much higher than existing home prices. Homebuilders say that is due to all the extra cost of regulation and not necessarily from higher input cost of lumber, cement, and worker wages. President Obama’s economists in fact wrote a white paper on the topic of lifting this burden. President Trump will likely try to move this issue – though jurisdictional issues of federal versus local will be contested.
  7. Fannie Mae and Freddie Mac may not survive. This would be most unfortunate. Let me be clear, these two institutions made horrendous business decisions in the past to buy subprime mortgages, create an internal hedge fund, and be led by political players in an attempt to serve political goals. That mistake cost hundreds of billions of taxpayer dollars. Fortunately, after management changes Fannie and Freddie today are led by technicians providing a government guarantee on soundly-written mortgages. As a result, they have repaid all the taxpayer bailout money. Moreover, they are doing so well financially given the very low mortgage default rates, that the U.S. Treasury is getting added revenue on the backs of responsible homeowners. If anything, the guarantee fees are too high and should be reduced. If Washington’s instinct is to eliminate Fannie and Freddie because of their past sins from past managers, then mortgages will be much more expensive with 30-year fixed rate products disappearing from the market place. Consider: mortgage lending on commercial real estate collapsed by over 90% a few years ago during the financial market crisis because there are no government guarantees for this product. Imagine what the housing market would be like if there was an equivalent crash of 90% reduction in home buying. We should view supporting Fannie and Freddie in the same way as we view supporting FDIC deposit government guarantee at banks – to help smooth the financial market.
  8. Community colleges are likely to get more help. That is because we need more workers with trade skills such as welders, plumbers, bricklayers, electricians, nurse assistants, and x-ray technicians. Some of these graduates will go into building homes and commercial real estate development. Interestingly, even though Mr. Trump and Secretary Clinton refused to shake hands, they both agreed on the greater role of community colleges in today’s economy.
  9. Homeowners in flood zones and who suffer through natural disasters may get much less relief from the government. Currently this federal program to assist in wild fires, hurricanes, earthquakes, and other natural disasters is $24 billion in the hole. The government instinct could be to reduce government’s role and have homeowners pay more. All risks should no doubt be properly priced. But the current flood map for federal insurance coverage is totally outdated and not useful. Rather than lessen the coverage on federal insurance more efforts should be made on updating the maps so a better risk assessment can be made.
  10. There will be active discussions on tax reform. The goal would be to simplify. Currently, the U.S. tax code is said to be thicker than the Bible – but without any of the good news. In simplifying, there could be a trimming of the mortgage interest deduction, reducing property tax deduction, and cutting of exemptions on capital gains from the sale of a home. Moreover, for commercial real estate practitioners, the like-kind exchange tax deferral (also known in the industry as 1031) could easily be on the chopping block. Research has consistently shown how valuable these tax preferences are for homeownership, in protecting private property rights, and for economic growth. People in real estate and property owners across the country should therefore be on alert about any policy discussion on these matters.

To read the full article click here: https://www.forbes.com/sites/lawrenceyun/2016/11/10/trump-presidency-and-impact-on-real-estate/#52564e5c40b7