This article has been archived, please login for access or subscribe now for a free trial.
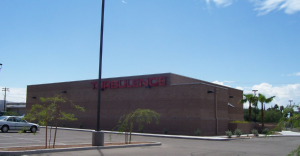
A Memphis-based company, 6608 Tucson Blvd, LLC (Steve Cooper, manager) bought Club Turbulence at 6608 S Tucson Blvd. in Tucson for approximately[mepr-show rules=”58038″]$1.54 million ($249 PSF) for the 6,176 sq. ft. Gentlemen’s Club located near the airport.
The property was built in 2005 by the seller, A & C Investments as an upscale Gentleman’s Club and has had several business owners. The broker told us the sale price was for the real property only and did not include the business. The buyer purchased the business in a separate transaction.
The buyer is an experienced club owner who owns and manages The Gold Club, an exotic dance club in Memphis.
Richard Spreiser of Spreiser Realty in Tucson, and member of the selling company, A & C Investments LLC handled the transaction.
Spreiser can be contacted at (520) 850-1640.[/mepr-show]
Small Business Confidence Showing Not Much Progress For a Recovery
*All net percentages seasonally adjusted unless otherwise noted.
By: Cynthia Magnuson-Allen and Holly Wade, Reprinted From the National Federation of Small Business Newsletter
The NFIB ‘s Small Business Economic Foundation surveys small business owner’s plans and opinions monthly. Decision makers at the federal, state and local levels actively monitor these reports, ensuring that the voice of small business is heard.
For the second consecutive month, small-business owner confidence edged up, according to NFIB’s Index of Small Business Optimism, which increased by 2.3 points to a final reading of 94.4 in May. While May’s reading is the second highest since the recession started December 2007, the Index does not signal strong economic growth for the sector. Eight of 10 Index components gained momentum, showing some moderation in pessimism about the economy and future sales, but planned job creation fell 1 point and reported job creation stalled after five months of gains.
“Small-business confidence rising is always a good thing, but it’s tough to be excited by meager growth in an otherwise tepid economy,” said NFIB chief economist Bill Dunkelberg. “Washington remains in a state of policy paralysis, and while the stock market sets records, GDP posts mediocre growth. The unemployment rate remains in the mid-7s and it is departures from the labor force—not job creation—that is contributing to its decline when it does fall. It’s nice to see confidence not shrinking, but there isn’t much to hang your hat on in this report. We are back to where we were in May 2012. Two good months don’t make a trend, but we can’t have a trend without them, so it’s a start.”
The small business half of GDP is not generating growth beyond population gains. More businesses are being formed than lost, but too many existing firms have not yet started to replace the workers shed during the recession. The Optimism Index is at its May 2012 level, which is identical to the November 2007 level. Since then, the Index has been higher in only three months, each time by less than 2 points.
Owners were asked to identify their top business problem: 24 percent cited taxes, 23 percent cited regulations and red tape, 16 percent cited weak sales and 2 percent reported financing/access to credit.
• Job Creation. Jobs creation fell for the first time since November 2012. Small employers reported an average gain of negative 0.04 workers per firm—essentially zero.
• Hard to Fill Job Openings. Forty-seven (47) percent of owners hired or tried to hire in the last three months and 38 percent (81 percent of those trying to hire or hiring) reported few or no qualified applicants for open positions.
• Sales. The net percent of all owners* reporting higher nominal sales in the past three months compared to the prior three months was unchanged at a negative 4 percent. While this is the best reading in nearly a year, there are still more firms reporting declines than gains. The net percent of owners expecting higher real sales volumes rose 4 points to 8 percent of all owners. Sales expectations are trending better, but are still historically weak.
• Earnings and Wages. Earnings trends improved 1 point over April’s reading, landing at a negative 22 percent. Three percent of small employers reduced worker compensation and 20 percent raised compensation, yielding a net 16 percent who reported higher worker compensation (up 1 point). A net 9 percent of owners plan to raise compensation in the coming months, unchanged in May.
• Credit Markets. Credit continues to be a non-issue for small employers, only 5 percent of whom say that all their credit needs were not met in May. This is down 1 point from April and the lowest reading since February 2008. Twenty-eight (28) percent of owners surveyed reported that all their credit needs were met last month, and 53 percent explicitly said they did not want a loan (67 percent including those who did not answer the question, presumably uninterested in borrowing as well).
• Capital Outlays. Owners put a few more dollars into capital expenditures in May; the frequency of reported capital outlays over the past six months rose 1 point to 57 percent in May. However, this is still 8 points below the average spending rate through 2007. Plans to increase expenditures stagnated, with 23 percent of owners planning capital outlays in the next three to six months.
• Good Time to Expand. In May, only 8 percent of owners characterized the current period as a good time to expand. This is up 4 points from a very weak reading in April, but still a poor showing when compared to an average value of 16 percent pre-recession. The net percent of owners expecting better business conditions in six months was a net negative 5 percent, 10 points better than April and 23 points better than March.
• Inventories. In May, a net negative 7 percent of all owners surveyed reported growth in inventories, one point below that reported in April. For all firms, a net 1 percent (up 2 points) reported stocks too low, an unusually “lean” level of satisfaction with inventory stocks. More owners are reducing stocks than adding to them, but the overall inventory picture was rather benign. Plans to add to inventories gained 3 points, rising to a net 3 percent of all firms.
• Inflation. The net percent of owners raising selling prices in May was 2 percent, down 1 point from April. Sixteen (16) percent of NFIB owners reported reducing their average selling prices in the past three months, and increase of 1 point, and 19 percent of owners surveyed reported price increases (down 1 point). As for prospective price increases, 17 percent of small employers plan to raise average prices in the next few months (down 4 points), and 3 percent plan price reductions. Seasonally adjusted, a net 15 percent plan price hikes, down 3 points.
The report is based on the responses of 715 randomly sampled small businesses in NFIB’s membership, surveyed throughout the month of May.
108 More Homes Being Constructed in Star Valley By Lennar Homes
Miramonte Holdings, Miramonte Homes and Borderland Star Valley of Tucson sold 108 finished residential lots to Lennar Homes of Arizona, a subsidiary of Lennar Corporation of Florida (NYSE:LEN), for $3.024 million, or $28,000 per lot in Block 18 at Star Valley. The 55′ x 110′ finished lots are in block 18 in the Master Planned Community of Star Valley off Camino Verde and Los Reales in southwest Tucson.
Lennar is not new to Star Valley, in 2010, Lennar purchased 123 finished lots in block 13 at Star Valley for $22,500 per lot.
Lennar Corporation (Stuart Miller, CEO), founded in 1954, is headquartered in Miami, Florida and is one of the nation’s leading builders of affordable, move-up and retirement homes in communities that cater to almost any lifestyle, urban, golf course, Active Adult or suburban. Lennar offers “everything included” homes on select models.
Will White of Arizona Land Advisors in Tucson represented the seller in these transactions. Contact Lennar Homes at (480) 345-0077 . Miramonte is at (520) 747-1644. White can be reached at (520) 514-7454.