TUCSON LEASE REPORT – JUNE 3 – JUNE 7, 2013

logo RED b&w 640 x 400INDUSTRIAL SPACE – 2165 N FORBES BLVD., STE 105, TUCSON

United Freight Service (Nick Sblendorio, President)  leased 17,618 sq. ft. at 2165 N Forbes Blvd, Suite 105 in Tucson from Forbes Tucson, LLC. United Freight Service is a floor covering logistics company with locations in Phoenix, Tucson, Las Vegas, San Diego, Los Angeles, and Dalton, GA. Rob Glaser, SIOR, CCIM, Industrial Specialist with Cushman & Wakefield / Picor Commercial Real Estate Service handled the transaction.

OFFICE SPACE – 5301 E GRANT   ROAD, TUCSON

Brown Mackie College leased 13,296 square feet at 5301 E. Grant Road in Tucson from TMC Holdings, Inc. Rick Kleiner, MBA, Tom Knox, SIOR, and Tom Nieman, Principals and Office Specialists with Cushman & Wakefield | PICOR Commercial Real Estate Services, handled the transaction. Kleiner and Knox represented the landlord and Nieman representing the tenant.

RETAIL SPACE – 825 E UNIVERSITY, TUCSON

CVS Pharmacy leased 12,000 sq. ft. at 825 E University at Main Gate Square in Tucson. CVS will be the newest addition to 20 retailers and 30 restaurants at Main   Gate Square near the University of Arizona. The landlord was the Marshall Foundation. CVS plans to be open by the start of school in late summer. Broker information was not available in time for publishing.

OFFICE SPACE – 6130 N LACHOLLA   BLVD, TUCSON

Northwest Hospital, LLC renewed two medical office leases at 6130 North LaCholla, Tucson, including 8,848 sq. ft. in Suite 111, and 9,851 sq. ft., Suite 121 from landlord HCP / Utah, LLC. Rick Kleiner, MBA, and Tom Knox, SIOR, Principals and Office Specialists with Cushman & Wakefield | PICOR Commercial Real Estate Services represented the landlord in these transactions.

STUDENT HOUSING – 95% LEASED AT LEVEL, 1020 N TYNDALL, TUCSON

Campus Acquisitions reported this week that Phase I of two student housing projects adjacent to the University of Arizona is 95% leased while work continues on Phase 2 on Park Avenue, the second tower for Fall 2014 delivery. LEVEL is a 14-story, 176-unit, 586 bed, upscale building, complete with modern amenities including a rooftop pool, outdoor terraces, exercise rooms, study and technology rooms, and on-site management by CA’s full service staff. LEVEL broke ground in May 2012 and will be ready for August 2013 occupancy.

OFFICE SPACE – WILMOT PROFESSIONAL PLAZA

Oasis Medical Aesthetics leased 3,025 sq. ft. at WilmotProfessionalPlaza located on Wilmot Rd., just south of Grant Rd. The premises will be used as a medical office specializing in cosmetic medical services and for the sales of related products and services. They are scheduled to open for business September 2013. Andy Seleznov and Melissa Lal, represented the landlord, Larsen Baker, while Jeff Casper, of CBRE in Tucson represented the tenant.

RETAIL SPACE – 7607 N ORACLE   ROAD, TUCSON

Fleet Feet Sports leased 2,890 square feet within Oracle Crossing Shopping Center at 7607 N. Oracle Road in Tucson from Weingarten Nostat, Inc. Aaron LaPrise, Retail Specialist with Cushman & Wakefield | PICOR Commercial Real Estate Services, represented the Tenant in this transaction.

RETAIL – TUCSON SPECTRUM NEW PAD

Five Guys Burgers & Fries leased 2,505 sq. ft. at TucsonSpectrumShopping Center at the southwest corner of I-19 and Irvington from DDR that will build the new pad 6,400 sq. ft. out parcel #6 between Harkins Theatres and Discount Tire. Chris Ray of Catalyst Commercial Group in Phoenix represented the tenant. Contact Nancy McClure of CBRE for information on the remaining space adjoining Five Guys Burgers and other availability at the Tucson Spectrum.

RETAIL – 2910 E   SPEEDWAY BLVD, TUCSON

LB Tucson Restaurant Company, LLC of Ramona, CA (Jose Bravo, manager)  leased 1,872 sq. ft. at 2910   E Speedway Blvd, a former KFC in Tucson, from the Elizabeth McCuiston Trust. Aaron LaPrise and Greg Furrier of Cushman & Wakefield / Picor Commercial Real Estate Services handled the transaction.

To submit sales or leases email [email protected]


Growth & Reductions for some National Retailers

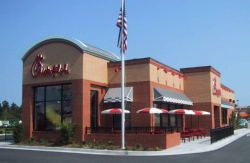
Chick-fil-A-exterior-lgRestaurant chain Chick-fil-A  plans to open 102 new locations across the country in 2013, including 78 stand-alone, one drive thru, four in-line and two mall restaurants to go along with 17 licensed locations. The company continued to grow in 2012, increasing the number of new restaurants initially planned for the year and reporting a record-setting annual sales of more then $4.6 billion in 2012.

Whole Foods says it plans to take “a good hard look” at parts of the Fresh & Easy chain that British retailer Tesco is divesting in California. Bolstered by healthy cash flow and no debt, the organic grocer plans to introduce 32 new stores during fiscal 2013 and an additional 33 to 38 units the following year. Tesco has announced that it intends to leave the US market and abandon the Fresh & Easy Neighborhood concept that has been losing money. The future of these 200 grocery stores remains in limbo, with lots of interest from potential buyers.

As the housing market begins to take hold, home improvement chains are again experiencing positive store sales growth and returning to expansion.  During the recession, comparable store sales from Home Depot and Lowe’s posted declines that peaked in 2008 and spurred the closing of a combined 105 locations between 2009 and 2012. Since then store sales have steadily improved and regained positive territory during 2010, a 2.9% sales increase for Home Depot and  1.3% growth for Lowe’s. In fiscal year 2012 growth improved to 4.6% for Home Depot and 1.4% for Lowe’s. Although Lowe’s has added more stores over the past two years, Home Depot remains the growth leader.

Lowe’s will continue to add new stores at a more measured pace in the near-term, remaining cautiously optimistic about the recent housing recovery. The home improvement chain introduced 10 new locations in 2012 and projects a similar number for the current year. Lowe’s expansion strategy is focused on under-penetrated urban markets where it believes it can take advantage of favorable site costs , reasonable municipal requirements, and attractive returns on investment.

Office supply chain Staples announced it will more aggressively trim its North American store base than previously projected. The company reported that it is on target for a reduction of 40 stores in 2013, compared to its earlier expectation of 30 stores.

Electronics retailer Best Buy has highlighted several priorities in its turnaround efforts, including accelerating online growth and optimizing its US real estate portfolio. The company closed 47 stores, while opening 105 Best Buy Mobile standalone units during 2012. Occupancy cost reductions continue to be a key focus for the company and it says it has made significant progress renegotiating leases. Additionally Best Buy will reduce space allocated to the negative growth and low margin CD and DVD categories while replacing it with higher grossing products like mobile, appliances, and accessories. The retailer plans to close an additional five to ten US Best Buy locations and open a small number of mobile units in 2013.


Sponsored by Stewart Title and Trust – The only title company named one of

 “AMERICA‘S MOST TRUSTWORTHY COMPANIES” in 2012 by Forbes®.

Contact Stewart Title & Trust of Tucson at (520) 327-7373 for your next closing.


Homeowners: FHA Changed The Rules on June 3rd

FHAstampFor the seventh time in 5 years, the Federal Housing Administration (FHA) raised its mortgage insurance premium (MIP) schedule for FHA-insured borrowers on April 1, 2013. As of June 3, HUD revised the FHA minimum time a borrower must hold mortgage insurance and rescinded the automatic cancellation of annual MIP.

FHA was a critical player during the housing bust, increasing eligible loan amounts to take the slack left by private mortgage insurance providers (PMI) that tightened guidelines so much they became unreliable for borrowers with less than 20% down. But lending during the bust, while helpful in preventing an even worse economic outcome, left the FHA short on reserves.

By 2010, the FHA’s Mutual Mortgage Insurance (MMI) account had dropped below $2 for every $100 insured, which was a violation of the agency’s congressional mandate. Through 2011, the losses continued and in 2012 the FHA showed a negative $1.44 for every $100 insured.

For this reason they are increased mortgage insurance fees April 1st and the length of time a borrower must pay them on June 3rd.

While this up-trend has been going on since 2010, when the annual premium was .55% to.6% of the loan amount, paid monthly. Compare that to the latest change with rate ranges up to 1.3% to 1.55%. In other words, on a 10% down scenario for a $500,000 loan today, the monthly mortgage insurance has increased to $542.

Going forward, on and after June 3, 2013, the FHA removed the exemption from annual MIP for loans with terms of 15 years or less and LTVs of less than or equal to 78% at origination. For everyone else with a LTV greater than 90%, including those making a 3.5% down payment, the FHA will assess MIP for the duration of the loan’s term, or the first 30 years of the term, whichever comes first.

For streamline refinances without appraisals, FHA uses the original appraised value of the property to calculate the LTV.

These new rules give the FHA more padding, but they remove the option and incentive for a borrower to pay extra to eliminate the mortgage insurance sooner.

Prior to this, if a borrower paid their normal mortgage payment (without making any extra principal payments), they would be able to eliminate their mortgage insurance in about 6 years—and if they wanted to do it more aggressively they could pay a bit extra to knock it out in 5 years.

With these new rates and terms, we may see the pendulum swing away from FHA and back toward private mortgage insurance (PMI) providers. The PMI companies have eased approval guidelines a bit as the recovery trudges on, and their fees are definitely less, with rates ranging from .64% to 1.02% depending on credit score (or $267/mo compared to $425 on that same $500,000 loan example used above). But their approval guidelines are more stringent than FHA.

So from here out borrowers will need to look at both options.