L.A. Insurance Agency Lease Brings Tucson’s El Campo Center to Full Occupancy

El Campo Center
El Campo Center

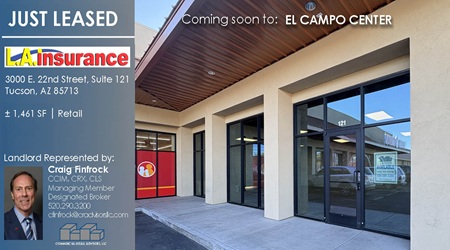
TUCSON, AZ (Oct 19, 2026) — L.A. Insurance Agency has leased 1,461 square feet at El Campo Center, 3000 E. 22nd Street, Suite 121, at the southwest corner of 22nd Street and Country Club Road. The transaction brings the shopping center to 100% occupancy.

Scheduled to open in January 2027, the office will be L.A. Insurance Agency’s fourth Tucson location and 14th in Arizona. The agency will offer vehicle title and registration services in addition to its insurance products.

L.A. Insurance Agency is one of North America’s largest independent insurance agency franchises, with more than 200 locations in seven states. Its insurance offerings include auto, motorcycle, RV and motorhome, renters, boat and watercraft, commercial auto, and life coverage.

Craig Finfrock of Commercial Retail Advisors, LLC represented the landlord, El Campo Center, LLC. L.A. Insurance Agency represented itself in the transaction.

Founded in 2001, Commercial Retail Advisors specializes in shopping center leasing and sales and retailer tenant representation throughout Southern Arizona. For more information, contact Craig Finfrock at (520) 290-3200 or visit www.cradvisorsllc.com.


333 Tower Lands Major Corporate User, Rooftop Restaurant and Bar Coming Soon

333 Tower
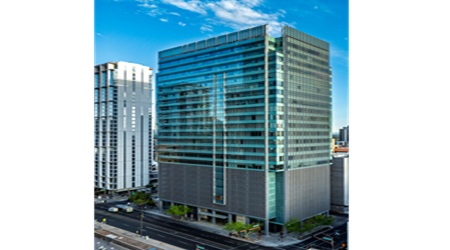
333 Tower, 333 N. Central Avenue in Downtown Phoenix

Phoenix, AZ (October 19, 2026) — Newmark and Foundation 8 announced that Trinity Capital has signed a long-term lease at 333 Tower, the iconic Class AA office tower located at 333 N. Central Avenue in Downtown Phoenix. The company will occupy the property’s top 2½ floors and secure prominent building-top signage rights.

Acquired by Foundation 8 at the end of 2025, the office component of 333 Tower is being transformed from a single-tenant occupancy model into a premier multi-tenant workplace destination designed to attract leading companies seeking high-quality headquarters space in the urban core.

Newmark Senior Managing Director Brett Abramson, Managing Director Chris Latvaaho and Director Chris Beall represented Foundation 8 in the transaction. Chris Nord & Nikki Tate of Cushman & Wakefield represented Trinity Capital.

Situated atop The Westin Phoenix Downtown, 333 Tower is a 26-story mixed-use high-rise offering expansive floor plates of approximately 30,000 square feet, floor-to-ceiling glass, structured parking and panoramic views across the Valley. Foundation 8 is investing significantly in the property’s next phase, including plans for a rooftop restaurant and bar, a ground-floor coffee shop and café, a dedicated conference center and additional hospitality-driven amenities designed to enhance the tenant experience.

“Trinity Capital’s commitment to 333 Tower is an important step in realizing our vision for the property,” said Kenneth Losch of Foundation 8. “We acquired the asset with the goal of creating one of Downtown Phoenix’s premier workplace destinations. This lease not only validates that vision but also establishes momentum as we continue to attract exceptional companies and invest in an unparalleled workplace experience.”

The lease signals growing demand for highly amenitized, large-block office opportunities in Downtown Phoenix and represents a milestone in Foundation 8’s broader business plan for the property.

“Phoenix has been our home since we started back in 2008, and that connection is central to who we are,” said Kyle Brown, CEO of Trinity Capital. “We’re excited about our growth trajectory here at TRIN and proud to remain committed to the innovative business community in Downtown Phoenix for many years to come.”

“We bought 333 Tower knowing the market had very little Class AA space remaining,” added Troy Harris of Foundation 8. “There is a clear flight-to-quality occurring, and with no new construction on the horizon, we knew we had something special with this building – Trinity Capital’s recent lease confirms that. With a rooftop bar and restaurant, as well as a ground-floor coffee bistro on the way, we’re excited about what’s next for 333 Tower.”

Approximately 165,000 square feet of office space remains available for lease at 333 Tower, including a large contiguous block suitable for headquarters users and growing companies seeking a highly visible presence in the urban core. Ownership is also actively seeking an operator for the property’s planned rooftop restaurant and bar, which will further enhance the building’s amenity offering and activate one of Downtown Phoenix’s most prominent rooftop destinations.

“333 Tower offers a combination of trophy quality, large block availability and an abundant amenity base that is increasingly difficult to find in today’s market,” said Abramson. “Foundation 8 has created a compelling vision for the property, and Trinity’s commitment is a strong endorsement of that strategy. We expect continued interest from tenants seeking a differentiated workplace environment in Downtown Phoenix.”

The tenant improvements for Trinity Capital and the property’s forthcoming hospitality offerings are being designed by DeBartolo Architects.

“333 Tower offers an opportunity to reimagine the workplace as an experience, one that brings together architecture, hospitality and human connection. Our approach is rooted in simplicity, clarity, and a deep respect for the building’s inherent qualities, using natural light, panoramic views, and thoughtful material choices to create spaces that engage the senses, support well-being, and connect people to place. The goal is to create an environment of enduring value that elevates the everyday experience of those who work and gather here,” said Jack DeBartolo III of DeBartolo Architects.


Phoenix Industrial Leasing Holds Firm as Construction Pipeline Expands to 21.1 Million Square Feet

Phoenix Industrial Leasing

PHOENIX, AZ (Oct. 19, 2026) — Phoenix’s industrial market recorded 9.6 million square feet of leasing activity in the third quarter of 2026, while a growing construction pipeline signaled a new development cycle, according to CBRE’s latest Phoenix Industrial Figures report.

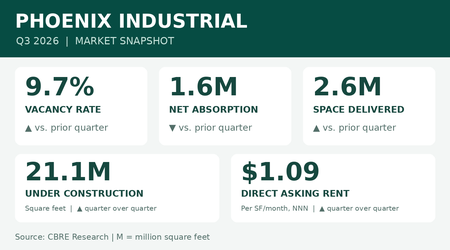
Tenant demand continued to absorb space, although occupancy gains slowed considerably from the previous quarter. Net absorption totaled 1.59 million square feet, down from 4.62 million square feet in the second quarter. Deliveries of approximately 2.6 million square feet exceeded absorption, pushing overall vacancy up slightly to 9.7%, compared with 9.6% the previous quarter.

Despite that quarterly increase, vacancy remained 150 basis points below its level a year earlier and 300 basis points below the recent peak of 12.7% in the first quarter of 2025. Availability, which includes some space still occupied but being marketed, declined to 11.2%, falling 30 basis points from the previous quarter and 130 basis points year over year.

The figures point to a market with continued leasing momentum but substantial differences among locations and building sizes.

The Southwest Valley remained the region’s primary leasing hub, generating approximately 4.8 million square feet of activity, or half the metropolitan total. The Southeast Valley followed with 3.1 million square feet, while the Airport Area contributed approximately 1.1 million square feet.

The quarter’s largest transaction was a confidential tenant’s lease of approximately 1.15 million square feet at 7842 N. Reems Road in the Southwest Valley. Other significant transactions included Magna Steyr USA’s 405,000-square-foot renewal and expansion at 7035 E. Pecos Road in the Southeast Valley.

Atkinson Industries leased 392,000 square feet at 17450 W. Minnezona Avenue, and Southland Industries leased 317,000 square feet at 9602 W. Indian School Road, both in the Southwest Valley. Across the market, leasing volume over the most recent four quarters reached 36.2 million square feet.

Strong leasing activity did not translate directly into occupancy gains in every submarket. The Southwest Valley posted negative net absorption of approximately 135,000 square feet, its first negative quarter in more than a decade, according to CBRE. A major contributor was UNIS vacating a roughly 900,000-square-foot warehouse.

The Southeast Valley led quarterly absorption with approximately 689,000 square feet, followed by the Airport Area with 494,000 square feet, the Northwest Valley with 403,000 square feet and the Northeast Valley with 143,000 square feet.

CBRE attributed much of the slowdown in overall absorption to limited availability of buildings larger than 750,000 square feet, despite continued demand for that product. Vacancy among buildings in that size category was just 3.1%, compared with 19.3% for buildings ranging from 100,000 to 249,999 square feet.

Developers are responding to demand for larger facilities. Space under construction reached 21.1 million square feet, up 12.5% from the second quarter and 85% from a year earlier. Although the pipeline has expanded sharply, it remained 47.5% below its third-quarter 2023 level.

The Southwest Valley accounted for approximately 10.97 million square feet under construction, followed by the Southeast Valley with 5.66 million square feet. Together, those two submarkets represented nearly 79% of the metropolitan pipeline.

Major projects included the 1.3-million-square-foot LG Energy Battery Manufacturing Facility in the Southeast Valley, along with Northern Parkway Logistics Center Building D and VT303 North in the Southwest Valley, measuring approximately 1.2 million and 1.1 million square feet, respectively. CBRE reported that both Southwest Valley projects were preleased. Marketwide, 36.5% of space under construction had been preleased.

Average direct asking rent stood at $1.09 per square foot per month on a triple-net basis. The Northeast Valley commanded the highest average at $1.75, while the Southwest Valley offered the lowest at $0.91.

Vacancy also varied considerably by location. The Northeast Valley had the lowest rate at 5.7%, followed by the Northwest Valley at 7.7%, the Airport Area at 8.4% and the Southwest Valley at 9.2%. The Southeast Valley recorded the highest vacancy at 13.1%, although that represented a 180-basis-point improvement from a year earlier.

For owners and developers, the quarter’s results underscore the importance of matching new supply to specific tenant requirements. Phoenix continues to attract substantial industrial commitments, but tight availability for the largest buildings coexists with greater competition for tenants in other size categories.

See the full CBRE Q3 report here.