Downtown Phoenix Office Tower Secures $44.5 Million Renovation Loan
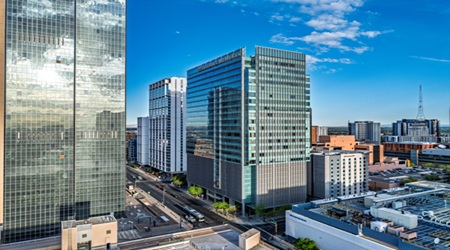
PHOENIX, ARIZONA (Sept. 21, 2026) — The new owner of the Phoenix office tower portion of 333 N. Central Avenue in downtown Phoenix has secured a $44.5 million loan to renovate and reposition the property for a broader mix of tenants.
The 26-story tower was built in 2010 and served for years as the headquarters of mining giant Freeport-McMoRan, which occupied eight floors totaling approximately 250,000 square feet. The company began vacating its space during the COVID-19 pandemic and formally terminated its lease in May, according to Maricopa County records.
The lower portion of the building contains the 242-room Westin Phoenix Downtown hotel and was not included in the office sale.
Phoenix-based real estate investment firm Formation 8 LLC acquired the upper portion of the tower from Peakstone Realty Trust in December 2025. The sale price was not disclosed, although the buyer obtained an $18 million loan at the time of acquisition. That loan was scheduled to mature Sept. 1, 2026, one day before the new financing was recorded.
Formation 8 plans to reposition the former single-user office space to accommodate multiple tenants. Renovations will focus primarily on build-to-suit improvements for incoming occupants, along with new amenities intended to make the property more competitive.
The project will also include removing the Freeport-McMoRan signage from the tower. The signage could eventually be replaced by branding for a future marquee tenant.
Newmark is leading leasing efforts and is actively marketing the available office space.
Hilco Global, a subsidiary of ORIX Corporation USA, provided the $44.5 million loan. The financing will support leasing costs, tenant improvements and the addition of new amenities. New York-based Sterling Realty Capital served as debt placement agent and financing adviser to Formation 8.
Formation 8 is also repositioning the former Sheraton Crescent Hotel near Interstate 17 and the former Metrocenter mall. The firm acquired the long-vacant property for $9.25 million in March. Its development group plans to invest approximately $400 million to convert the property into 1,786 apartment units.