Dutch Bros and 7 Brew Compete for Former Salad and Go Sites
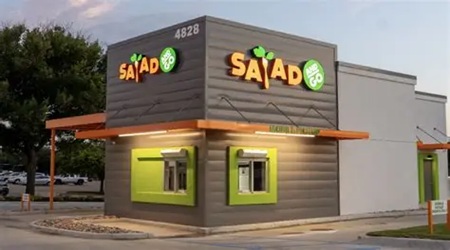
Salad and Go(August 13, 2026) — Salad and Go’s bankruptcy has created an unexpected expansion opportunity for two of the country’s fastest-growing drive-thru beverage operators.

Dutch Bros was initially reported as the buyer for dozens of former Salad and Go locations, with the transaction valued at approximately $105 million. Reports have varied on the number of properties involved, ranging from 51 to as many as 65 locations.

The deal, however, may not be settled.

7 Brew has challenged the proposed transaction in bankruptcy court, arguing that its offer could generate a better financial outcome for creditors. The dispute could potentially result in a broader bidding process for the portfolio.

At stake is something increasingly difficult to assemble in today’s retail market: a large collection of existing drive-thru sites with long-term leases already in place.

Rather than building dozens of locations one at a time, either Dutch Bros or 7 Brew could potentially establish a major block of new stores across Arizona and Nevada in a relatively short period.

That is what makes the Salad and Go portfolio especially valuable.

According to an analysis by Chris Rodriguez of DealGround, 65 Salad and Go locations in Arizona and Nevada carry average annual rents of approximately $120,000. Individual rents reportedly range from about $94,000 to $209,000 annually.

Most of the leases also have substantial term remaining, generally more than 10 years, with many extending another 13 to 14 years before renewal options are exercised.

In a retail market where development costs and land prices have risen sharply, those lease terms could be difficult to replicate today.

The former Salad and Go buildings are generally small, ranging from approximately 650 to 1,000 square feet, but their existing drive-thru configurations make them particularly attractive to beverage operators.

Both Dutch Bros and 7 Brew would likely need to adapt their prototypes to fit some of the locations, but the economics are very different when an operator is evaluating dozens of stores instead of a single property.

A portfolio acquisition could allow either company to accept design compromises that would normally make little sense on an individual site.

The opportunity may be especially important in Arizona, where both brands continue to expand aggressively.

For landlords, the competition could prove beneficial.

A vacant Salad and Go building is not necessarily an easy property to retenant. The small building size and specialized drive-thru format narrow the universe of potential users.

If a location were rejected during the bankruptcy process, an owner could face significant downtime or redevelopment costs before securing another tenant.

The arrival of two competing operators changes that equation.

Instead of negotiating with a single prospective replacement tenant, some landlords could find themselves holding leases that both Dutch Bros and 7 Brew want to assume.

That competition may reduce the pressure on landlords to offer rent concessions or other incentives.

The credit profile of the replacement tenant could also affect property values.

Dutch Bros operates its newer stores corporately rather than through traditional franchising. A 7 Brew transaction could involve franchise operators depending on territorial agreements and how individual leases are ultimately assigned.

For landlords, those differences could influence financing, resale value and investor demand.

Bankruptcy court considerations, however, extend beyond which tenant a landlord might prefer. The court’s primary responsibility is maximizing the value of the bankruptcy estate for creditors.

That means the winning proposal will likely depend on overall economics, certainty of closing and the ability of the acquiring company to perform under the leases.

The process could take time as competing offers, lease assignments and individual property issues are evaluated.

The broader real estate lesson is familiar.

Single-tenant properties are often purchased because of the tenant occupying them, but the long-term value of the investment ultimately depends on the real estate itself.

A strong location can survive the loss of a tenant. A weak location can become a problem the moment the rent stops.

The Salad and Go portfolio provides an unusually clear example.

For some landlords, the bankruptcy could have resulted in vacant specialty buildings with few obvious replacement users. Instead, two expanding national brands are competing for many of the same sites.

That is a far better outcome than most owners could have expected when Salad and Go began closing stores.

Who ultimately wins the portfolio remains to be determined.

For Dutch Bros and 7 Brew, however, the attraction is obvious: dozens of drive-thru locations, established lease terms, and the opportunity to accelerate growth without waiting years to assemble a comparable pipeline through traditional development.


Mining Executive Buys Northwest Tucson Office Building for $2.135 Million

Northwest Tucson Office

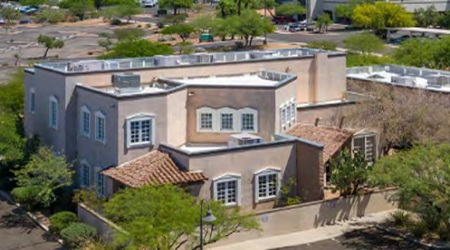
TUCSON, ARIZONA (Aug. 12, 2026) — Cruztel de Sonora LLC, an entity represented by veteran mining executive Jesse S. Muñoz and Leslie Muñoz, purchased The Watermark Building at 2020 W. Rudasill Road in northwest Tucson for $2.135 million.

The approximately 8,906-square-foot office building is situated on one acre near La Cholla Boulevard and Orange Grove Road. The transaction closed July 28, 2026. The sale equates to approximately $239.73 per square foot. Cruztel de Sonora acquired the property to owner-occupy it.

Muñoz is Executive Director and owner of Tucson-based Tes Oro Mining Group LLC, a mining consulting and project development firm serving domestic and international mining operations. According to the Tes Oro website, Muñoz has more than 33 years of experience in the mining sector, including management roles with the American Girl, El Dorado, and Western Mesquite mines. He has also served as Director and Chief Operating Officer of Marlin Gold Mining Ltd. and as COO of Mako Mining Corp.

Tes Oro provides services throughout the mining development cycle, including exploration, project evaluation, engineering, metallurgy, mine development, construction management, commissioning and operations. Its work includes projects in Mexico and Latin America.

The buyer was represented in the Rudasill Road acquisition by Ryan McGregor of Cushman & Wakefield | PICOR.

The seller, Watermark 2020 LLC, an affiliate of Watermark Retirement Communities, was represented by Gordon Wagner and Ben Craney of NAI Horizon.

Built in 1997 with an additional 1,160 square feet constructed in 1998, the two- and three-story building includes approximately 1,184 square feet of basement space housing a server room, studio, and storage area. The property sits within The Fountains at La Cholla development.

The acquisition will provide an owner-occupied Tucson location for Muñoz’s mining-related business activities.

For more information, Wagner can be reached at 520.326.2200, and Craney is at 520.326.4500. McGregor should be reached at 520.271.2657.

Source: RED Comp #12638


JLL closes $79.35M sale of specialized industrial properties in Metro Phoenix

specialized industrialMorgan Stanley Real Estate Investing acquires Honeywell Aerospace-occupied facility in Chandler and aviation maintenance campus near Sky Harbor Airport

PHOENIX, (Aug. 12, 2026) – JLL Capital Markets announced today the $79.35 million sale of a two-property industrial portfolio in Metro Phoenix featuring mission-critical facilities with highly specialized infrastructure and long-term lease commitments.

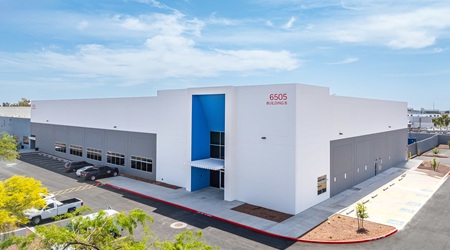
The portfolio includes AMPlify Chandler, a 196,764-square-foot industrial facility fully occupied by Fortune 100 aerospace and advanced manufacturing leader Honeywell Aerospace, and AMPlify Riverpoint, an 80,309-square-foot aviation maintenance and training facility fully leased to the Aviation Institute of Maintenance.

JLL represented the seller, Phoenix Rising Investments LLC and an affiliate of Blue Vista Capital Management, LLC, in the transaction. Funds managed by Morgan Stanley Real Estate Investing (MSREI) acquired the assets.

AMPlify Chandler at 6505 W. Chandler Blvd. is located less than a mile from Interstate 10 and Loop 202 interchange in Chandler. Originally built in 1981, the property was renovated in 2025 with a new approximately 40,000-square-foot expansion building specifically designed to meet Honeywell’s operational requirements. The facility features an on-site, fully owned and property-dedicated 50MW substation, positioning it as a heavy-infrastructure industrial asset capable of supporting advanced manufacturing operations.

AMPlify Riverpoint at 4025 S. 32nd St. includes two aircraft hangars housing seven training aircraft, along with technical labs, a composite shop and specialized industrial space. The property features prominent I-10 freeway frontage adjacent to the completed Broadway Curve Improvement Project and is positioned at the center of a growing aviation and technical employment hub near Phoenix Sky Harbor International Airport.

“Over the past seven years, we’ve transformed this facility into a state-of-the-art advanced manufacturing campus through strategic capital investment and close collaboration with Honeywell,” said Michael Hsiung, co-founder of Phoenix Rising Investments. “With Honeywell’s long-term lease commitment extending beyond 2030, we’re confident this asset will continue to serve as a critical manufacturing hub under MSREI’s stewardship.”

The JLL Capital Markets team was led by Senior Managing Directors Ben Geelan and Carl Beardsley, Senior Director Greer Oliver, Associate Bryce Beecher and Senior Analyst Gigi Martin. Local market expertise was provided by JLL’s leasing team, led by Vice Chairman Steve Larsen, Managing Director Jason Moore and Senior Managing Directors Pat Harlan and Kyle Westfall.

“Phoenix is still in the early innings of a structural demand cycle that will reshape how capital evaluates industrial assets across the Southwest,” Geelan said. “Manufacturing tenants are making site selection decisions based on power availability and specialized configurations rather than just freeway access, and investors who recognize this transition early will benefit from long-term fundamentals that extend well beyond traditional distribution-focused underwriting.”