Phoenix Industrial Leasing Holds Firm as Construction Pipeline Expands to 21.1 Million Square Feet
PHOENIX, AZ (Oct. 19, 2026) — Phoenix’s industrial market recorded 9.6 million square feet of leasing activity in the third quarter of 2026, while a growing construction pipeline signaled a new development cycle, according to CBRE’s latest Phoenix Industrial Figures report.
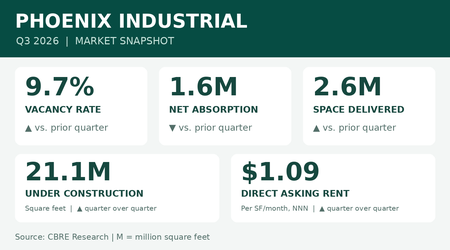
Tenant demand continued to absorb space, although occupancy gains slowed considerably from the previous quarter. Net absorption totaled 1.59 million square feet, down from 4.62 million square feet in the second quarter. Deliveries of approximately 2.6 million square feet exceeded absorption, pushing overall vacancy up slightly to 9.7%, compared with 9.6% the previous quarter.
Despite that quarterly increase, vacancy remained 150 basis points below its level a year earlier and 300 basis points below the recent peak of 12.7% in the first quarter of 2025. Availability, which includes some space still occupied but being marketed, declined to 11.2%, falling 30 basis points from the previous quarter and 130 basis points year over year.
The figures point to a market with continued leasing momentum but substantial differences among locations and building sizes.
The Southwest Valley remained the region’s primary leasing hub, generating approximately 4.8 million square feet of activity, or half the metropolitan total. The Southeast Valley followed with 3.1 million square feet, while the Airport Area contributed approximately 1.1 million square feet.
The quarter’s largest transaction was a confidential tenant’s lease of approximately 1.15 million square feet at 7842 N. Reems Road in the Southwest Valley. Other significant transactions included Magna Steyr USA’s 405,000-square-foot renewal and expansion at 7035 E. Pecos Road in the Southeast Valley.
Atkinson Industries leased 392,000 square feet at 17450 W. Minnezona Avenue, and Southland Industries leased 317,000 square feet at 9602 W. Indian School Road, both in the Southwest Valley. Across the market, leasing volume over the most recent four quarters reached 36.2 million square feet.
Strong leasing activity did not translate directly into occupancy gains in every submarket. The Southwest Valley posted negative net absorption of approximately 135,000 square feet, its first negative quarter in more than a decade, according to CBRE. A major contributor was UNIS vacating a roughly 900,000-square-foot warehouse.
The Southeast Valley led quarterly absorption with approximately 689,000 square feet, followed by the Airport Area with 494,000 square feet, the Northwest Valley with 403,000 square feet and the Northeast Valley with 143,000 square feet.
CBRE attributed much of the slowdown in overall absorption to limited availability of buildings larger than 750,000 square feet, despite continued demand for that product. Vacancy among buildings in that size category was just 3.1%, compared with 19.3% for buildings ranging from 100,000 to 249,999 square feet.
Developers are responding to demand for larger facilities. Space under construction reached 21.1 million square feet, up 12.5% from the second quarter and 85% from a year earlier. Although the pipeline has expanded sharply, it remained 47.5% below its third-quarter 2023 level.
The Southwest Valley accounted for approximately 10.97 million square feet under construction, followed by the Southeast Valley with 5.66 million square feet. Together, those two submarkets represented nearly 79% of the metropolitan pipeline.
Major projects included the 1.3-million-square-foot LG Energy Battery Manufacturing Facility in the Southeast Valley, along with Northern Parkway Logistics Center Building D and VT303 North in the Southwest Valley, measuring approximately 1.2 million and 1.1 million square feet, respectively. CBRE reported that both Southwest Valley projects were preleased. Marketwide, 36.5% of space under construction had been preleased.
Average direct asking rent stood at $1.09 per square foot per month on a triple-net basis. The Northeast Valley commanded the highest average at $1.75, while the Southwest Valley offered the lowest at $0.91.
Vacancy also varied considerably by location. The Northeast Valley had the lowest rate at 5.7%, followed by the Northwest Valley at 7.7%, the Airport Area at 8.4% and the Southwest Valley at 9.2%. The Southeast Valley recorded the highest vacancy at 13.1%, although that represented a 180-basis-point improvement from a year earlier.
For owners and developers, the quarter’s results underscore the importance of matching new supply to specific tenant requirements. Phoenix continues to attract substantial industrial commitments, but tight availability for the largest buildings coexists with greater competition for tenants in other size categories.
See the full CBRE Q3 report here.